

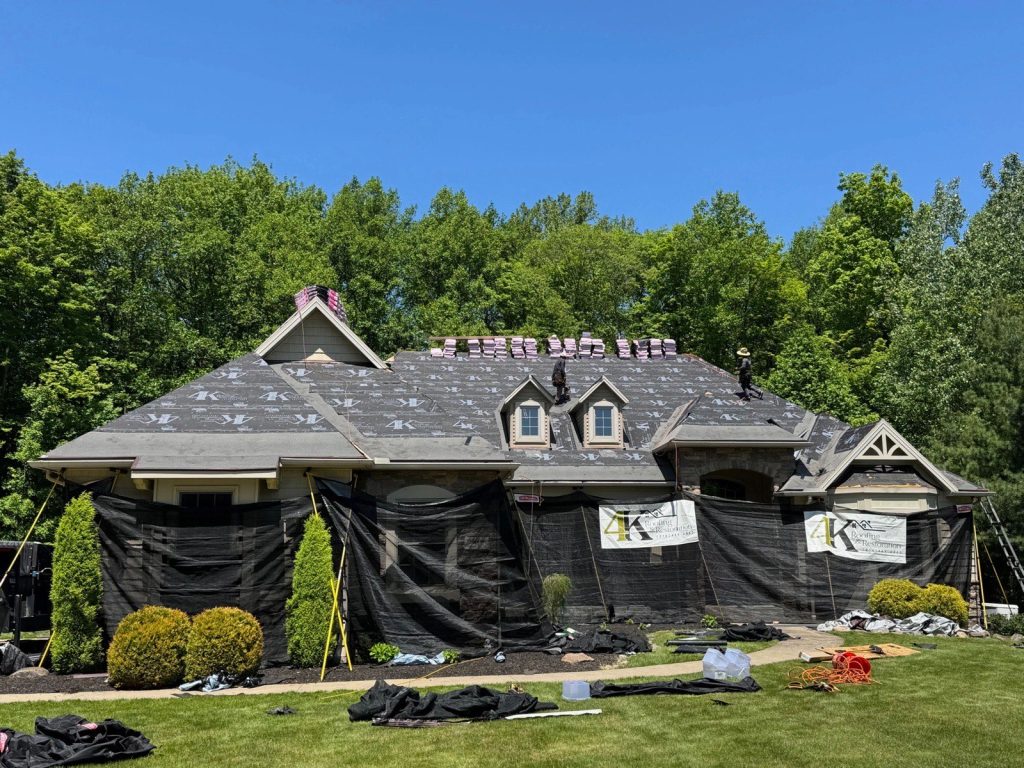
The first estimate your insurance company sends is rarely the final one, and signing off without a contractor review can leave thousands on the table. The adjuster came, walked your roof, took some photos, and handed you a number. Now you are staring at an estimate that feels low, a list of line items you do not fully understand, and a deadline to respond.
This is what is happening right now across Medina, Brunswick, Wadsworth, and the rest of Northeast Ohio in the weeks after the April storms. Homeowners who called their insurer first, got an adjuster out, and are now trying to figure out if the number they got is fair. Most of the time, it is not.
What adjusters miss, and why
Insurance adjusters are not roofing contractors. They are trained to assess damage from a coverage standpoint, not from a contractor’s standpoint. Those are two different things. Common items that get missed or undervalued:
- Soft metal damage. Your gutters, vents, and flashing take hail hits the same way your shingles do. Adjusters routinely miss dents on soft metals because they are not as visible as shingle bruising. A contractor knows exactly where to look and how to document it.
- Functional versus cosmetic damage. Insurance companies in Ohio will sometimes classify bruised shingles as cosmetic. A contractor who knows the policy language can push back on that classification. The difference in payout can be significant.
- Ventilation and decking. If hail impact compromised your shingles enough, there is a real chance the underlayment and decking below took damage too. That does not show up on a surface inspection. It shows up when a contractor does a proper assessment.
- Code upgrade requirements. Ohio building codes have changed. When a roof gets replaced, it often has to be brought up to current code. That cost is frequently not included in the initial estimate. It should be.
What your policy probably covers that you do not know about
Read the declarations page of your homeowner’s policy and look for these. Replacement Cost Value versus Actual Cash Value: if your policy is RCV, your insurer is required to pay the full replacement cost, not the depreciated value. Some homeowners do not know which they have, and insurers do not always volunteer the distinction. Supplemental claims: even after your initial estimate is approved, you can file a supplement if a contractor finds additional damage during the actual replacement. This is standard practice and does not void your claim. Code upgrade coverage, sometimes called Ordinance or Law: some policies include a rider that specifically covers the cost of bringing a roof up to code during replacement. If yours does, make sure it is reflected in your estimate.
The window is closing
Ohio insurance policies have claim filing deadlines. For most standard homeowner policies, you have one year from the date of loss to file. That sounds like a lot of time, but the practical window is shorter. The longer you wait, the harder it becomes to connect the damage directly to a specific storm event. Adjusters look for that connection. Contractors who document damage properly give you a much stronger case. If your adjuster has already been out and you have not had an independent contractor review that estimate, do it before you respond.
What to do right now
You do not have to face the insurance process alone, and you do not have to accept the first number they give you. Get a second set of eyes on your roof before you sign anything. A contractor who works insurance claims regularly knows exactly how to document damage, what line items are missing, and how to work with your adjuster to get you a fair settlement.
4K Roofing and Restoration has handled hundreds of insurance claims across Medina County and Northeast Ohio. We know what Ohio adjusters miss, we know how to document it, and we work directly with your insurer so you do not have to. Free inspection, no pressure. We will tell you straight whether your estimate looks right. Call 216.469.0863 or schedule your free roof inspection online.